Go Program Way2Go Card
Conduent IncorporatedFinanceVerified
- 24.40K Reviews
- 3.5
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
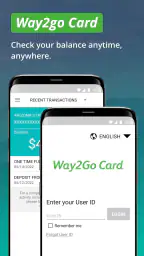
I found Go Program Way2Go Card most useful when I treated it as a focused account-checking tool rather than a complete personal-finance app. Its job is straightforward: it gives cardholders a practical way to watch available funds and transaction activity from a phone. That narrow purpose is also its biggest strength. I do not open it expecting budgeting charts, investment tools, or a replacement for a full bank app. I open it when I need a quick answer about the money connected to my Way2Go Card.
That distinction matters because finance apps often try to do everything at once. This one, developed by Conduent Incorporated, stays centered on the card experience. It is free, carries an Everyone content rating, and has been available since August 14, 2015. With more than a million installs and a 3.5 average from roughly fifty-eight thousand ratings, it is clearly used by a substantial number of cardholders, although the rating also suggests that the experience is not equally smooth for everyone.
What using the card app is actually like
The most valuable part of the app is the immediate view of your available balance. In everyday use, that can prevent the small but stressful mistakes that happen when you rely on memory, an old receipt, or a delayed mental calculation. I can check before making a purchase, confirm whether a recent payment appears in the account, and review activity without searching through paper records.
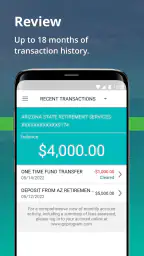
I especially like the distinction between checking available funds and simply remembering how much money should be there. A balance is only useful if it reflects the activity that matters to you. Looking at the transaction history after a purchase gives me a second layer of confidence: I can see whether the activity has appeared and notice anything that does not look familiar.
A realistic example is using the card for several necessities during a busy week. I might buy groceries, pay for transportation, and make another small purchase without keeping a running total. Before the next payment, I can open the app, check the available amount, and scan the recent activity. That takes less effort than reconstructing the week from memory and is exactly the kind of small routine that makes a dedicated card app worthwhile.
The app is also helpful for separating “I think I have enough” from “I have checked.” That is a modest benefit, but it is important for a card connected to essential spending. I would rather spend a few seconds reviewing the current screen than discover at checkout that my assumption was wrong.
A focused tool instead of a full banking dashboard
My main judgment is that Go Program Way2Go Card works best as a companion to the card itself. It is not the right place to organize every part of your financial life. If you want a complete monthly budget, savings goals, bill planning, credit monitoring, or a broad view of several unrelated accounts, a conventional bank app or dedicated budgeting service will be more suitable.
Other Stories to Read




That is not a criticism of the app’s basic purpose. In fact, the limited scope makes it easier to understand what to do when I open it. The important question is usually one of three things: how much is available, what recently happened, and whether the activity matches my expectations. A specialized screen can be more useful than a crowded financial dashboard when that is all I need.
The trade-off is that I would still need another method for wider money management. I would not use this as my only financial application. A separate note, spreadsheet, bank service, or budgeting app may be necessary if I want to plan upcoming expenses or compare spending across accounts. The Way2Go Card app can inform those decisions, but it does not replace the planning process.
Where the transaction view earns its place
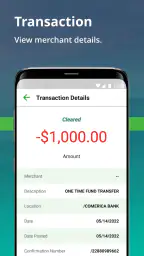
The transaction activity is more than a decorative history list. I use it as a quick verification step. After a card purchase, checking the activity can help me keep my own records current. If I am helping a family member manage card spending, the history also gives us something concrete to discuss instead of relying on vague recollections.
One useful habit is to review activity at a consistent time rather than only when something goes wrong. A short check after essential purchases can make unfamiliar entries easier to recognize because the surrounding context is still fresh. This is particularly practical for people who make several small transactions and otherwise lose track of them.
Another good workflow is to pair the app with a simple personal spending note. I can record an upcoming obligation separately, then use the app to confirm what is actually available before relying on that note. The two tools serve different purposes: my note helps me plan, while the app shows the card’s current position. Treating them as complements avoids expecting the app to become a full budgeting system.
There is also a useful caution here. Seeing a transaction in the activity list does not automatically explain every detail about it. If something looks unfamiliar, I would first compare the timing and amount with receipts or recent purchases before assuming the card has been compromised. If it still does not make sense, I would use the appropriate support route connected with the card rather than trying to solve a serious dispute through repeated app refreshes.
The friction I would want new users to anticipate
The average rating of 3.5 tells me to keep expectations realistic. A focused finance app can be extremely useful when it opens and shows the information I need, but even a small interruption feels more serious when the task involves available money. A login problem, slow loading, or confusing activity entry can turn a ten-second check into an aggravating experience.
I also think the app’s usefulness depends heavily on the cardholder’s situation. Someone who only needs a reliable view of card activity may find its narrow design sensible. Someone expecting the polish and breadth of a major bank’s mobile platform may find it limited. The app should be judged against its purpose, but that purpose is not broad enough for every financial routine.
One practical limitation is that checking the balance does not remove the need for personal judgment. The number on screen can tell me what is available, but it cannot create a spending plan or decide whether an upcoming expense is wise. I still need to account for purchases I intend to make, obligations outside the card, and any timing issues that affect my decisions. The app is a useful reference point, not a financial adviser.
I would also avoid using the transaction screen as my only record for long-term organization. A card history is convenient for recent checking, but people who need to prepare a detailed monthly review may prefer to copy important entries into a separate system. That extra step is not a flaw in the basic balance-checking function; it is simply the consequence of choosing a specialized tool over a full financial organizer.
Small habits that make it more useful
I get more value from the app when I open it before, rather than after, an important purchase. That simple change turns the balance screen into a decision aid. It is especially helpful when several recent transactions may have changed what I can safely spend.
I also recommend checking the activity after a purchase that matters, not just checking the balance. The balance answers “how much is available?” while the history helps answer “what changed?” Those are different questions, and using both screens gives a clearer picture than relying on either one alone.
For people who share household responsibilities, a useful arrangement is to make the app the common reference point while keeping private planning notes elsewhere. That avoids passing around screenshots or depending on one person’s memory. It also makes conversations about spending more precise: the card activity can be reviewed first, and the household can then decide how to handle upcoming needs.
Finally, I would keep the app updated when a newer version is offered through the relevant store. The current version is 3.3.5, and staying current is a sensible maintenance habit for any finance application. It does not guarantee a perfect experience, but it reduces the chance of knowingly relying on an outdated installation.
Who should choose it, and who should look elsewhere?
I would recommend Go Program Way2Go Card to someone who actively uses a Way2Go Card and wants a direct mobile way to check available funds and recent transactions. It is also a reasonable choice for a cardholder who prefers a simple, purpose-built screen over a large banking application full of unrelated features.
It can be particularly useful for people who need frequent reassurance before spending, who want to build a habit of reviewing card activity, or who help another person keep track of card use. The free price removes an obvious barrier, and the Everyone age rating makes it broadly approachable as a general card-management tool.
I would be more hesitant to recommend it as the main finance app for someone with several accounts, detailed budgeting needs, or a strong preference for advanced financial analysis. That person will probably be happier with a bank app that combines accounts or a budgeting service designed around categories, goals, and longer-term planning. I would also suggest looking elsewhere if the app’s focused balance-and-activity role does not match the cardholder’s daily needs.
The number of reviews, around twenty-four thousand, suggests that many users have taken the time to describe their experiences, while the overall rating indicates a mixed picture rather than universal satisfaction. I read that as a reason to try it with a practical mindset: use it for the information it is designed to provide, but keep an alternative way to manage important records and decisions.
My final take
After using it as a card companion, I see Go Program Way2Go Card as a useful but deliberately narrow finance app. Its strongest evidence is the everyday workflow: open it, check what is available, review recent activity, and make a more informed spending decision. That is not a glamorous feature set, but it addresses a real need without forcing the user through a full banking dashboard.
Its meaningful weakness is the same narrowness. It does not become a budgeting system simply because it shows transactions, and a middling 3.5 average means I would not promise every cardholder a frictionless experience. The app is best when the question is about the Way2Go Card itself, not about an entire household’s financial picture.
My recommendation is therefore specific. If you have a Way2Go Card and want a free, direct way to monitor available funds and card activity on a supported device running at least iOS 10, I think it is worth trying. If you want broad financial planning, account aggregation, or detailed spending analysis, choose a more comprehensive alternative and keep this app, at most, as a focused card-checking tool. Its value comes from doing one important job clearly, not from pretending to replace every other finance app.
For me, that makes it a practical recommendation with sensible boundaries. I would keep it installed for quick checks, use the activity view as part of a regular spending routine, and maintain separate records for longer-term planning. That combination respects what the app does well while avoiding the frustration that comes from asking it to do more than its focused design can reasonably provide.
Highlights
- Quickly check your Way2Go Card balance and recent transactions.
- Mobile access makes managing benefits convenient while traveling.
- Card details and account information are available in one place.
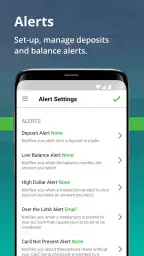
- Transaction alerts can help you monitor card activity more closely.
- Useful support resources are accessible directly from the app.
Limitations
- Some features may require a stable internet connection to load properly.
- Login or security verification can feel inconvenient during urgent access.
- App usefulness depends on your state or program supporting Way2Go services.
- Transaction updates may not appear immediately after a purchase.
- Users may still need customer support for complex card issues.
Frequently Asked Questions
01What is the Go Program Way2Go Card used for?
The Go Program Way2Go Card is a prepaid debit card commonly used by participating government agencies to distribute benefits, payments, or other funds electronically. Instead of receiving a paper check, eligible users can access their money through the card. The exact purpose, eligibility rules, and available services depend on the agency that issued your card.
02How do I activate my Go Program Way2Go Card?
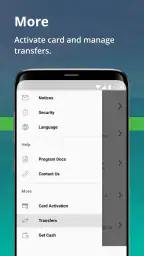
After receiving your card, you generally need to activate it before making purchases or withdrawing cash. Activation is usually completed through the official Way2Go Card website, mobile application, or the customer service telephone number printed on the card. You may be asked to provide the card number, security information, and personal details for identity verification.
03Can I manage my card through the Go Program Way2Go app?
The official Go Program Way2Go app may allow eligible cardholders to review balances, check transaction history, locate nearby ATMs, manage notifications, and access account information. Available features can vary by state, program, and card type. Before downloading, confirm that the app is the official version and that your issuing agency supports mobile account management.
04Are there fees for using the Go Program Way2Go Card?
Some Way2Go Card services may be free, while others can involve fees. Possible charges may apply to certain ATM withdrawals, out-of-network transactions, replacement cards, balance inquiries, or additional services. Fee policies differ according to the issuing program, so carefully review the cardholder agreement and current fee schedule before using the card.
05What should I do if my Go Program Way2Go Card is lost, stolen, or not working?
If your card is lost, stolen, declined, or suspected of unauthorized use, contact Way2Go Card customer service as soon as possible using the official number printed on the card or provided by your agency. Promptly reporting the issue can help protect your funds. Avoid sharing your PIN, full card number, or login credentials with unofficial websites or callers.


